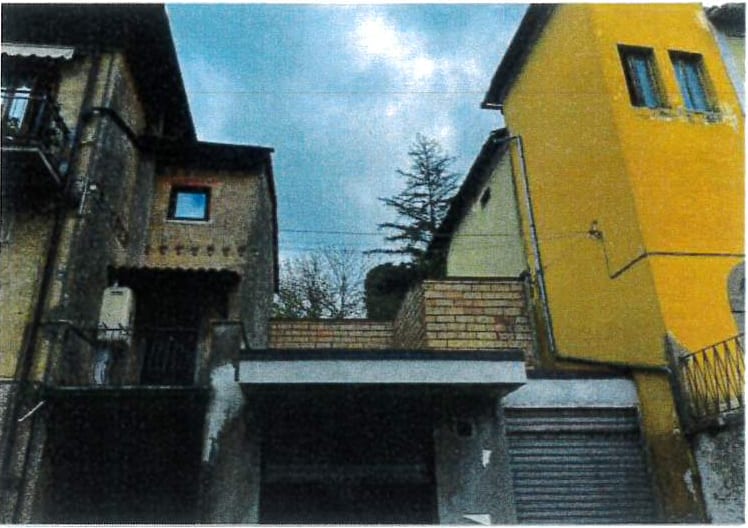
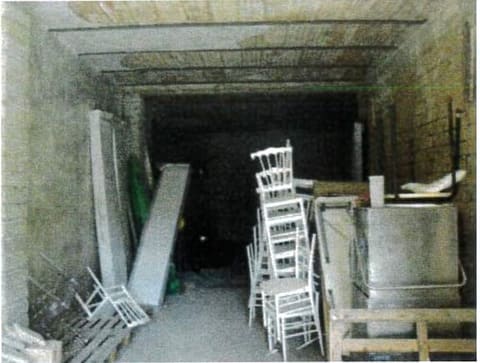
- Type
- Immobile commerciale · magazzino
- Area
- 10 m² · cat. C/2
- Cadastral details
- Sheet 252 parcel 2
- Procedure
- Court of Roma · Liquidazione Giudiziale (cci) n. 260/2026
Cadastral documents
For the parcel of the lot
- Cadastral record and report for the parcel
What you are buying
The parcels are confirmed in the cadastre of the Agenzia delle Entrate (Italian Revenue Agency), with the official areas. Area, cadastral details and compliance are read automatically from the documents of the procedure: the official valuation report prevails.
Original description · from the source, in Italian
Risks
HIGH IMPACT
It does not match the filed plans
Unico ambiente per eliminazione dei tramezzi divisori tra le particelle 198 e 2 sub 7; tramezzi interni non conformi alle planimetrie catastali…
Price per m² · vs area¹
The stated area (10 m²) gives a €/m² that is off the scale, usually because it includes land or outbuildings. At the area's prices for magazzini (500–700 €/m²) €5,500 buys 8–11 m²: if the property is larger, the reserve price is below market. Check it against the valuation report.
all property types in the area (OMI · Agenzia delle Entrate)
| Property type | €/m² (min–max) |
|---|---|
| magazzini | 500–700 |
| negozi | 900–1,600 |
Purchase taxes
Taxes for a sale at the reserve price. In a bankruptcy, a judicial liquidation or a composition with creditors the seller is a business, and the notice of sale says whether VAT applies: it does when the business built or renovated the property, always in the first five years and afterwards if it opts for it. Without VAT the registration tax is due, and the €100 are the mortgage and cadastral taxes. The taxes are counted on the price. First-home relief applies if it becomes an appurtenance of your first home, one per category among C/2, C/6 and C/7; with VAT, if it becomes an appurtenance of another home, the rate is 10%. Law: DPR 633/1972, art. 10 n. 8-bis e Tabella A, parte II n. 21 e parte III n. 127-undecies; DPR 131/1986, Tariffa parte prima art. 1 e art. 40. Source: Agenzia delle Entrate, guida «L'acquisto della casa», ottobre 2025, checked on 2026-10-28.
On the map
open the full map (cadastre, risks, constraints) ↗ · Cadastral map of Viterbo
Documents and bidding
The documents (valuation report, notice of sale, court orders) come from the Portale delle Vendite Pubbliche, the official register of the Ministry of Justice. The bid form and visit booking are on the Portale page ↗.
Mortgages, attachments and registered deeds are in the property registers, not in the cadastre: you check them with a mortgage search (ispezione ipotecaria); if you need a document with evidential value there is the mortgage certificate (certificato ipotecario).
¹ OMI price ranges, Agenzia delle Entrate (Italian Revenue Agency) · the official notice of sale prevails